Broadcom
Hock Tan
Data verified as of Sep 18, 2026
Summary
Broadcom Inc. is a Palo Alto semiconductor and infrastructure-software company whose legal lineage runs from Hewlett-Packard's 1961 semiconductor group through Avago Technologies to the 2016 takeover of Broadcom Corporation. Under CEO Hock Tan it is now the leading merchant designer of custom AI accelerators (XPUs) and AI Ethernet silicon for hyperscalers and frontier labs, while VMware, Symantec enterprise security, and mainframe software make up a high-margin infrastructure-software segment. Fiscal 2025 revenue was $63.9 billion (+24%), with AI semiconductor sales of $20.2 billion. The AI ramp then steepened: Q3 FY2026 (ended August 2, 2026) delivered record revenue of $29.6 billion (+86% YoY), including $16.7 billion of AI semiconductors (+221% YoY, +54% QoQ) across six XPU customers. Management raised FY2026 AI semiconductor guidance to $58 billion and said it has secured supply to roughly double that to $115 billion in FY2027 and again to $230 billion in FY2028, with Anthropic on track to become the largest XPU customer in 2027 on Google TPU Ironwood and TPU v8i, OpenAI's Jalapeno inference chip targeting 1.3 GW in 2027, and Google TPU plus networking locked through 2031. Q4 FY2026 is guided to about $34.8 billion of total revenue and $21.7 billion of AI semiconductors. The stock closed September 17, 2026 at $347.30, a market cap of about $1.66 trillion, well below the April 2026 $2 trillion print after several post-earnings selloffs on guidance that beat history but not the most aggressive estimates. Non-AI chips (Apple wireless and RF through 2031, broadband, storage) and VMware remain large, while a March 2026 CISPE complaint keeps EU scrutiny on VMware licensing.
Main Products
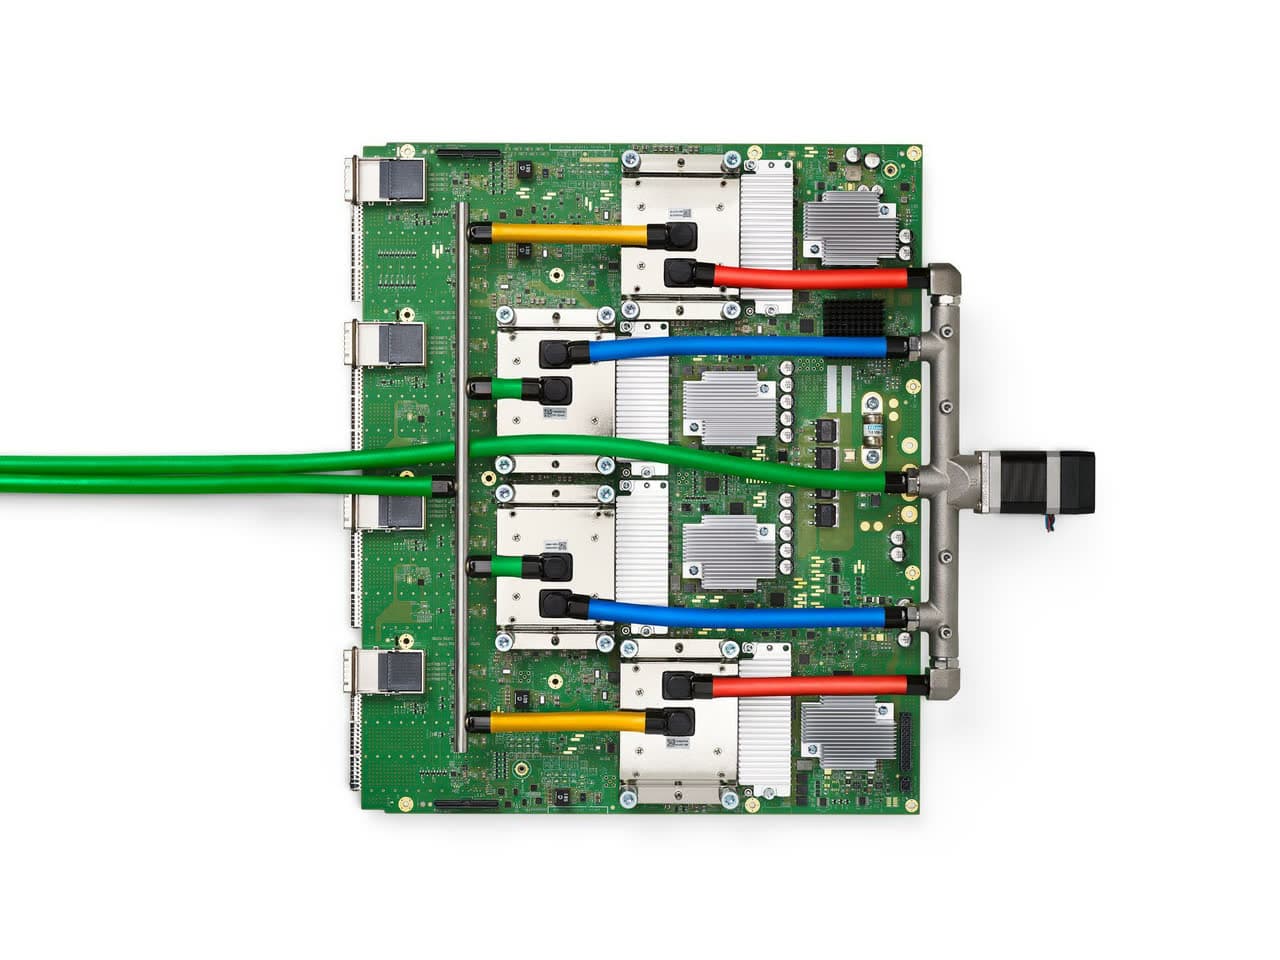
Broadcom's custom ASIC / XPU franchise co-designs accelerators with hyperscalers and frontier labs: Google TPUs (every generation since the program began, now contracted through 2031), Meta MTIA (extended through 2029, including a 2nm device), OpenAI Jalapeno (LLM-inference chip taped out in nine months), and Anthropic capacity on Google TPU Ironwood and TPU v8i. Broadcom owns the silicon implementation, HBM PHY, SerDes/network I/O, and 3.5D XDSiP face-to-face packaging; TSMC and, under a July 2026 MOU, Samsung manufacture. Q3 FY2026 XPU shipments grew more than 3.5x year over year and were 73% of AI semiconductor revenue.
Ironwood TPU v7 in high volume to Anthropic and Google; TPU v8i in initial production for Google; Jalapeno first-generation units shipping; next OpenAI XPU approaching tape-out
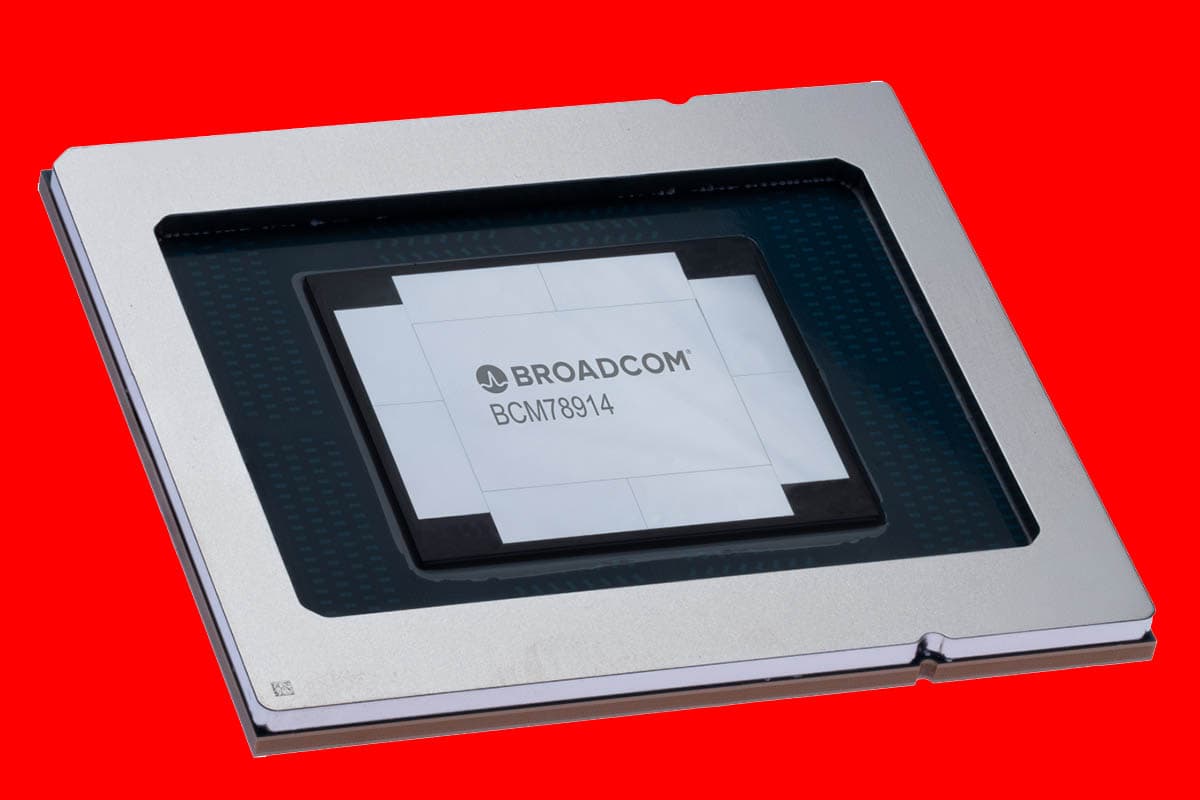
World's first 102.4 Tbps Ethernet switch chip (BCM78910 series), implemented in 3nm, with 512 x 200GbE or 1,024 x 100G SerDes, Cognitive Routing 2.0, and a co-packaged-optics variant (TH6-Davisson) using TSMC COUPE optical engines. Built for AI scale-up (512 XPUs in one domain) and two-tier scale-out (100,000-plus XPUs). Volume production was confirmed in March 2026 after first shipments in June 2025. AI networking, of which Tomahawk is the flagship, was almost 40% of Broadcom's AI semiconductor revenue in Q2 FY2026 and more than 2.5x year over year in Q3.
Shipping in production volume since March 2026; Davisson CPO variant shipping; used in Jalapeno scale-up/scale-out fabrics
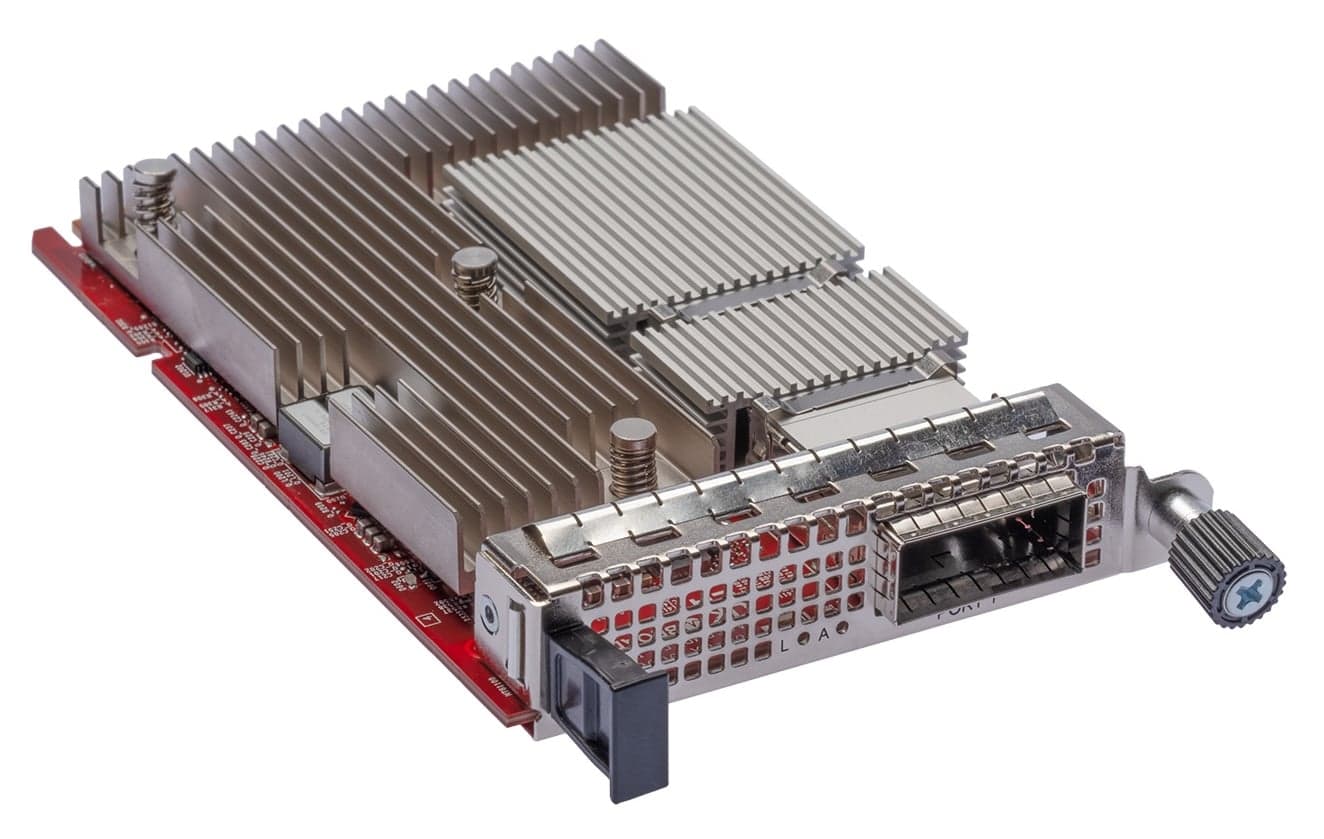
Industry's first 800G AI Ethernet NIC fully compliant with Ultra Ethernet Consortium 1.0, introduced October 14, 2025. Clean-sheet RDMA design (not a dual-400G bond) with packet-level multipathing, out-of-order placement into XPU memory, hardware SACK, programmable congestion control, PCIe Gen 6 x16, and line-rate PSP encryption. Ships as P1800GO (PCIe) and N1800GO (OCP 3.0) 800GbE adapters. Paired with Tomahawk 6, Tomahawk Ultra, Jericho 4, and Scale-Up Ethernet as Broadcom's open Ethernet alternative to proprietary GPU-scale fabrics.
Announced October 2025; 800GbE OCP 3.0 and PCIe adapters listed as active on Broadcom's network-adapter catalog
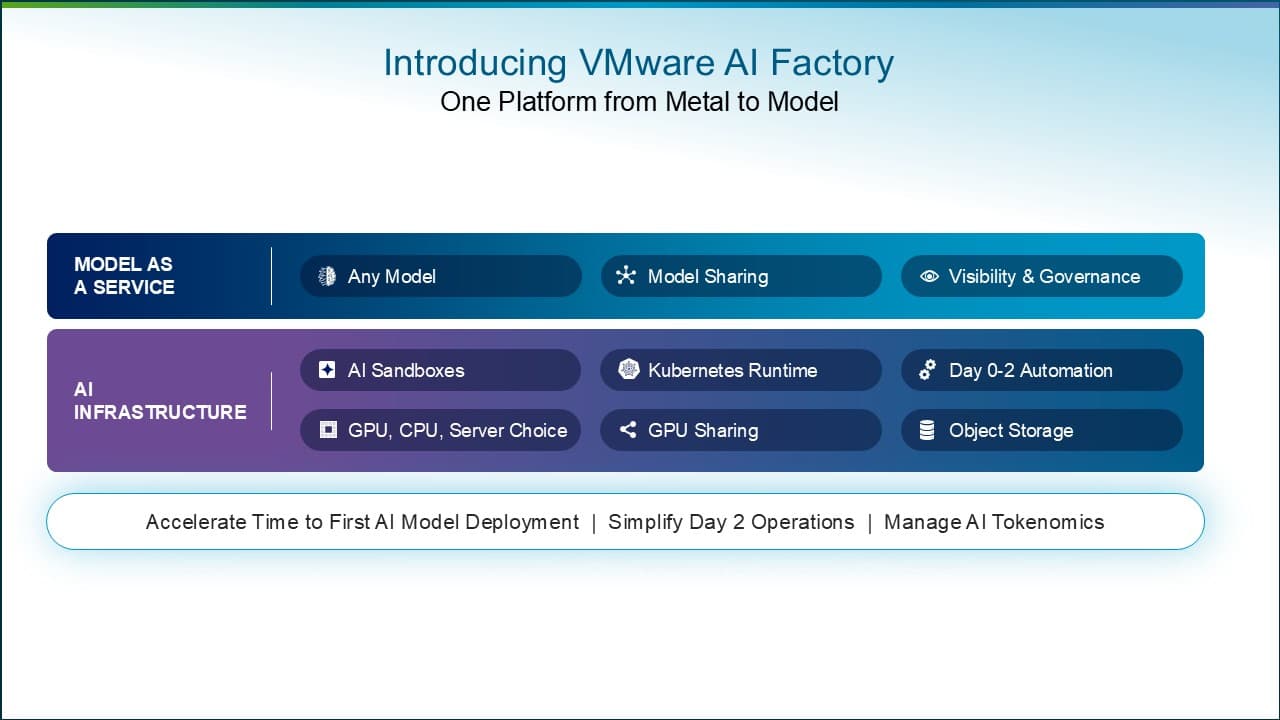
Broadcom's private-cloud software platform, inherited in the November 2023 VMware deal and now the core of infrastructure-software revenue. VCF 9.0 shipped in 2025; VCF 9.1 (May 2026) added production-AI features (memory tiering, storage dedupe, multi-accelerator GPU choice). At VMware Explore 2026 Broadcom layered VMware Private AI Cloud and VMware AI Factory on VCF for on-prem inference and agentic apps, plus AgentMinder for agent governance. VMware ARR was still growing about 15% in Q3 FY2026. EU cloud providers (CISPE) filed a March 2026 complaint alleging post-acquisition licensing abuses.
VCF 9.1 generally available; Private AI Cloud and AI Factory announced August 31, 2026; VMware Explore 2027 set for May 3-6, 2027
Broadcom's first full Wi-Fi 8 (IEEE 802.11bn / Ultra High Reliability) silicon ecosystem for residential gateways, enterprise access points, and client devices. Flagship parts include the BCM6719 4x4+4x4 dual-band AP chip, BCM4918 AI-ready network processor with an on-die Neural Engine, and May 2026 integrated SoCs (BCM6772/6774/6776) for mesh and multi-gigabit routers. A May 2026 collaboration with Samsung puts Broadcom Wi-Fi 8 alongside Samsung 5G modems for fixed-wireless access. Combined with RF front-ends, this line is the core of the Apple wireless relationship extended through 2031.
Wi-Fi 8 silicon shipping/sampling across residential, enterprise, and FWA; Apple custom wireless and RF extended through 2031
What's Next
Deliver Q4 FY2026 AI semiconductor revenue of $21.7 billion
Hock Tan guided Q4 FY2026 (ended November 1, 2026) AI semiconductor revenue to $21.7 billion, up 236% year over year, and total revenue to about $34.8 billion. That print is the near-term test of whether the Q3 XPU and networking ramp is still accelerating. Watch the mix of XPUs vs AI networking and whether non-GAAP operating margin holds near 66%.
Tape out OpenAI's next-generation XPU beyond Jalapeno
On the September 2, 2026 call Tan said Broadcom and OpenAI are deep in development of the successor to Jalapeno and that it is approaching tape-out, with a third generation already in development. Jalapeno itself is on track for 1.3 GW in 2027 and more than 5 GW of Jalapeno plus successor in 2028.
Deploy 1.3 GW of OpenAI Jalapeno in 2027
Jalapeno is OpenAI's first custom inference chip. Small-volume deployment was planned from late 2026 with a larger 1.3 GW tranche in 2027 inside the October 2025 10 GW collaboration that runs through 2029. Watch whether racks actually land on that 1.3 GW schedule and how much inference load moves off Nvidia GPUs.
Scale Anthropic from 1 GW Ironwood to 5 GW of TPU v8i
Management's Q3 FY2026 outlook puts 1 GW of Ironwood into Anthropic in 2026, another 5 GW of TPU v8i in 2027, and an incremental 10 GW in 2028, making Anthropic Broadcom's largest XPU customer in 2027 and 2028 even as Google continues to grow. The April 2026 8-K contractual language was about 3.5 GW beginning 2027, contingent on Anthropic's success, so the 5 GW / 10 GW figures are management's deployment outlook, not the same as the 8-K.
Print about $115 billion of AI semiconductor revenue in FY2027
Tan said Broadcom has secured the supply to double FY2026's $58 billion AI guide to about $115 billion in FY2027, and that demand already exceeds that outlook. A second doubling to about $230 billion is the FY2028 figure, with a target to exceed $30 of EPS that year. Any slip in hyperscaler or frontier-lab capex, or in HBM/foundry supply, would show up here first.
Convert the $200 billion Samsung MOU into a definitive supply contract
The July 25, 2026 Samsung memorandum covers HBM4/HBM4E, 2nm-and-below foundry, and advanced packaging through 2030 and is estimated at more than $200 billion. It is an MOU, not a signed purchase contract. Watch conversion to binding wafers, HBM, and packaging capacity, which would diversify Broadcom away from a TSMC-only XPU supply chain.
Stand up VMware Explore 2027 and the Private AI Cloud stack
VMware Explore 2027 moves to May 3-6, 2027 at Resorts World Las Vegas. Between now and then the test is whether Private AI Cloud, AI Factory, and AgentMinder turn into production enterprise deployments on VCF 9.1 rather than conference branding, and whether EU review of VMware cloud-provider licensing changes the software growth rate.
Track Record
3 of 3 announced dates hit
Operations & Revenue
Broadcom is running as a dual-engine company: custom AI XPUs and AI Ethernet on one side, VMware and the rest of infrastructure software on the other. Q3 FY2026 (ended August 2, 2026) set records for revenue ($29.6B), operating profit, and free cash flow ($13.7B). AI semiconductor revenue of $16.7B was 56% of the company, with high-volume Ironwood TPU v7 to Anthropic and Google, first TPU v8i production to Google, and first-generation OpenAI Jalapeno shipments. Semiconductor solutions were 70% of revenue ($20.8B); infrastructure software 30% ($8.8B, +29% YoY) with VMware ARR still growing mid-teens. Amie Thuener succeeded Kirsten Spears as CFO on June 12, 2026. Near-term watch items are Q4 AI semiconductors vs the $21.7B guide (quarter ends November 1, 2026), whether the $115B/$230B FY2027-28 AI outlook survives any slowdown in frontier-lab training spend, converting the Samsung $200B MOU into a signed supply contract, OpenAI's 1.3 GW Jalapeno deployment in 2027, and EU review of VMware cloud-provider licensing after the March 2026 CISPE complaint. Customer concentration in a handful of hyperscalers and labs is the structural risk next to TSMC/Samsung process and HBM supply.
Revenue Streams
AI semiconductors (XPUs + AI networking)
Custom AI accelerators co-designed with hyperscalers and frontier labs (Google TPU, Meta MTIA, OpenAI Jalapeno, Anthropic TPU capacity) plus AI Ethernet switches, NICs, SerDes, and optics. $16.7B in Q3 FY2026 (73% XPU / remainder networking); FY2026 guided to $58B. This is now the company's growth engine and more than half of quarterly sales.
Non-AI semiconductors (wireless, broadband, storage)
RF front-ends, Wi-Fi/Bluetooth, broadband/PON, Fibre Channel and server-storage controllers. Apple is a multi-year wireless and custom-ASIC customer through 2031. Q3 FY2026 non-AI semiconductor revenue was about $4.2B (+5% YoY, flat QoQ), with broadband and storage offsetting weaker wireless.
Infrastructure software (VMware, Symantec, CA/mainframe)
VMware Cloud Foundation and related private-cloud software, Symantec enterprise security, and CA mainframe and enterprise tools. Q3 FY2026 infrastructure-software revenue was $8.75B (+29% YoY), 30% of sales, with VMware sustaining about 15% ARR growth. Gross margins in this segment remain in the low-90s on a non-GAAP basis. EU cloud providers have complained about post-acquisition VMware licensing.
Key Metrics
- Employees
- approximately 33,000 (as of Nov 2, 2025)
- Est. Annual Revenue
- $63.89B in FY2025 (ended Nov 2, 2025, +24% YoY; GAAP net income $23.13B). Q3 FY2026 added $29.59B. Three-quarter FY2026 revenue is already $71.09B; Q4 guided to about $34.8B implies roughly $106B for full FY2026 if the guide holds
- Market cap
- about $1.66T (Sep 17, 2026 close; AVGO $347.30). 52-week high $495.00, low $289.96. Hit $2T in April 2026, the sixth company ever to do so
- Latest quarterly revenue
- $29.59B (Q3 FY2026, ended Aug 2, 2026, +86% YoY). Q4 guided to about $34.8B (+93% YoY). YTD three-quarter revenue $71.09B
- AI semiconductor revenue
- $16.7B in Q3 FY2026 (+221% YoY, +54% QoQ; 56% of total revenue). XPU shipments >3.5x YoY and 73% of AI revenue; AI networking >2.5x YoY. Q4 AI guided to $21.7B (+236% YoY). FY2026 AI guided to $58B (+186% YoY)
- AI revenue outlook
- about $115B in FY2027 and $230B in FY2028, on supply Tan said is already secured; demand 'exceeds' the FY2027 figure. Target to exceed $30 of EPS in FY2028
- XPU customers
- Six custom-accelerator customers. Named deployments include Google TPU (through 2031), Anthropic (largest XPU customer expected in 2027-2028; 1 GW Ironwood in 2026, 5 GW TPU v8i in 2027, incremental 10 GW in 2028), OpenAI Jalapeno (1.3 GW in 2027; >5 GW Jalapeno plus successor in 2028), and Meta MTIA (through 2029)
- Free cash flow
- Q3 FY2026 record $13.7B (46% of revenue); cash and equivalents $24.0B at quarter-end. FY2025 free cash flow $26.9B
- Non-GAAP operating margin
- about 66% in Q3 FY2026 (non-GAAP operating income $20.1B); Q4 guided to about 66% of projected revenue
Timeline
On April 6, 2026 Broadcom files an 8-K: a long-term agreement to develop and supply Google's future TPU generations plus a supply-assurance deal for networking and other AI-rack components through up to 2031, and an expansion under which Anthropic will access about 3.5 GW of next-generation TPU compute through Broadcom beginning in 2027, contingent on Anthropic's commercial success.
On April 14, 2026 Broadcom and Meta announce a multi-year, multi-generation partnership for Meta's MTIA custom accelerators through 2029, including a 2nm AI compute accelerator. The initial commitment exceeds 1 GW as the first phase of a multi-gigawatt rollout.
On June 9, 2026 Broadcom, Apollo, and Blackstone launch the AI XPV Platform to finance more than 20 GW of XPU and networking deployments for frontier labs through 2028. It opens with a $35 billion tranche, led by Apollo with Blackstone, for more than 1 GW of Anthropic capacity at Fluidstack sites from mid-2026.
On June 24, 2026 OpenAI and Broadcom unveil Jalapeno, OpenAI's first custom intelligence processor for LLM inference, designed to tape-out in nine months with Broadcom silicon implementation, Tomahawk networking, and Celestica boards and racks. Engineering samples run GPT-class workloads; gigawatt-scale deployment is planned with partners through 2029.
On July 6, 2026 Broadcom says it will develop and supply custom semiconductor products to Apple through 2031. Apple later frames the US manufacturing piece as more than $30 billion, with Broadcom investing $1.5 billion to expand its Fort Collins, Colorado RF and wireless plant, covering FBAR filters, Wi-Fi, Bluetooth, and other networking silicon used across Apple devices.
On July 25, 2026 Samsung Electronics and Broadcom sign a memorandum of understanding they estimate at more than $200 billion through 2030, covering HBM4/HBM4E memory, 2nm-and-below foundry, and 2.3D/2.5D advanced packaging for Broadcom AI accelerators. The MOU is not yet a definitive supply contract.
On September 2, 2026 Broadcom reports Q3 FY2026 (ended August 2) revenue of $29.59 billion (+86% YoY), semiconductor solutions $20.84 billion (+127%), infrastructure software $8.75 billion (+29%), and AI semiconductor revenue of $16.7 billion (+221% YoY, +54% QoQ). GAAP net income is $13.09 billion; free cash flow is a record $13.7 billion (46% of revenue). Hock Tan guides Q4 AI semiconductors to $21.7 billion and FY2026 AI to $58 billion, with FY2027/FY2028 AI outlook of about $115 billion and $230 billion on secured supply. Shares still sell off on the print, a now-familiar pattern of extraordinary numbers missing the most aggressive estimates.
At VMware Explore 2026 (August 31-September 3, Las Vegas), Broadcom launches VMware Private AI Cloud and VMware AI Factory on Cloud Foundation 9, plus AgentMinder for AI-agent governance. It also sets VMware Explore 2027 for May 3-6, 2027 at Resorts World Las Vegas.
On September 15, 2026, after Anthropic CEO Dario Amodei's 'pace the frontier' essay rattled AI-infrastructure stocks (AVGO -4.8% that day), Tan tells CNBC Mad Money that demand for training and inference compute remains strong and durable and that the FY2027 $115 billion and FY2028 $230 billion AI semiconductor projections are intact. He also says Anthropic is positioned to surpass other custom-chip buyers at Broadcom by 2027.
Fiscal 2025 (ended November 2, 2025) posts record revenue of $63.9 billion (+24%) and GAAP net income of $23.1 billion. Semiconductor solutions contribute $36.9 billion and infrastructure software $27.0 billion. AI semiconductor revenue grows 65% to $20.2 billion. Year-end headcount is about 33,000.
On October 13, 2025 OpenAI and Broadcom announce a collaboration to deploy 10 gigawatts of OpenAI-designed AI accelerators, with racks using Broadcom Ethernet, starting in the second half of 2026 and completing by end of 2029. The next day Broadcom introduces Thor Ultra, the first 800G AI Ethernet NIC compliant with the Ultra Ethernet Consortium spec.
On November 22, 2023, Broadcom completes its cash-and-stock acquisition of VMware, one of the largest deals in tech, after global antitrust review including China. CEO Hock Tan relocates headquarters from San Jose to VMware's Stanford Research Park campus in Palo Alto.
Broadcom Limited redomiciles from Singapore to Delaware as Broadcom Inc. The Trump administration blocks its hostile takeover of Qualcomm on CFIUS national-security grounds. In November it closes an $18.9 billion acquisition of mainframe and enterprise-software vendor CA Technologies, the start of a software diversification after the Qualcomm failure.